Are Denver Condos a Good Buy Right Now? What Buyers Should Know About Prices, HOA Fees, and Negotiating Power
If you've been trying to buy a home in Denver but detached-home prices and higher mortgage rates keep pushing the monthly payment outside your comfort zone, there's one part of the market I think deserves a closer look right now: condos and townhomes.
The latest Denver Metro housing numbers show that attached homes are behaving very differently from detached properties. According to the Denver Metro Association of REALTORS®, attached homes ended September with 7.21 months of inventory and a median closed price of $365,500, down 6.28% from a year earlier.
Compare that with Denver's detached-home market, which finished September with 4.08 months of inventory and a median closed price of $635,000.
That's a pretty significant difference.
For buyers, more inventory generally means more properties to compare, less pressure to make an immediate decision, and potentially more room to negotiate with sellers. For someone who has assumed Denver homeownership is simply out of reach, condos and townhomes may open up options that weren't there in the detached market.
But here's the catch: a lower price doesn't automatically mean you're getting a good deal.
HOA dues, insurance, special assessments, deferred maintenance, building finances, and even the ability to finance a particular condo can completely change the equation. The opportunity in Denver's condo market is real, but finding it requires looking beyond the price on the listing.
Why Denver Condos Look Different From Detached Homes Right Now
Metro-wide housing statistics can sometimes hide more than they reveal.
September ended with 4.76 months of inventory across the overall Denver Metro market, according to DMAR. That's much closer to a balanced market than the extremely tight conditions buyers dealt with earlier this decade.
Break the numbers apart, though, and things get more interesting.
Detached homes had 4.08 months of inventory and a September median closed price of $635,000. Attached homes, including condos and townhomes, had 7.21 months of inventory and a median closed price of $365,500.
The attached median was also down 6.28% compared with September 2025.
Now, that does not mean every Denver condo lost 6.28% of its value. Median prices reflect the properties that actually sold during a particular period, and conditions can vary dramatically from one neighborhood or building to another.
What it does tell us is that buyers currently have considerably more leverage in the attached market than they do in many parts of the detached market.
And that's the part I think is worth paying attention to.
Higher Mortgage Rates Make the Price Difference More Important
There's another reason condos are worth talking about right now: borrowing money has gotten more expensive.
Freddie Mac reported that the average 30-year fixed mortgage rate reached 7.40% on October 8, following seven consecutive weekly increases. A month earlier, the average was below 7%.
Higher rates reduce purchasing power regardless of what type of property you're buying. So when the median attached home is selling for substantially less than the median detached home, that price difference matters.
But don't make the mistake of comparing purchase prices and stopping there.
With a condo, you also need to factor in HOA dues, property taxes, homeowners insurance, potential special assessments, and what expenses the association pays on your behalf.
For example, a $375,000 condo with a $700 monthly HOA payment may not be nearly as affordable as the purchase price makes it look. On the other hand, a $500 HOA payment isn't automatically terrible if it includes water, heat, exterior maintenance, roof replacement, snow removal, trash, building insurance, or amenities you would otherwise pay for separately.
The HOA number by itself doesn't tell you much.
You need to know what you're actually getting for the money.
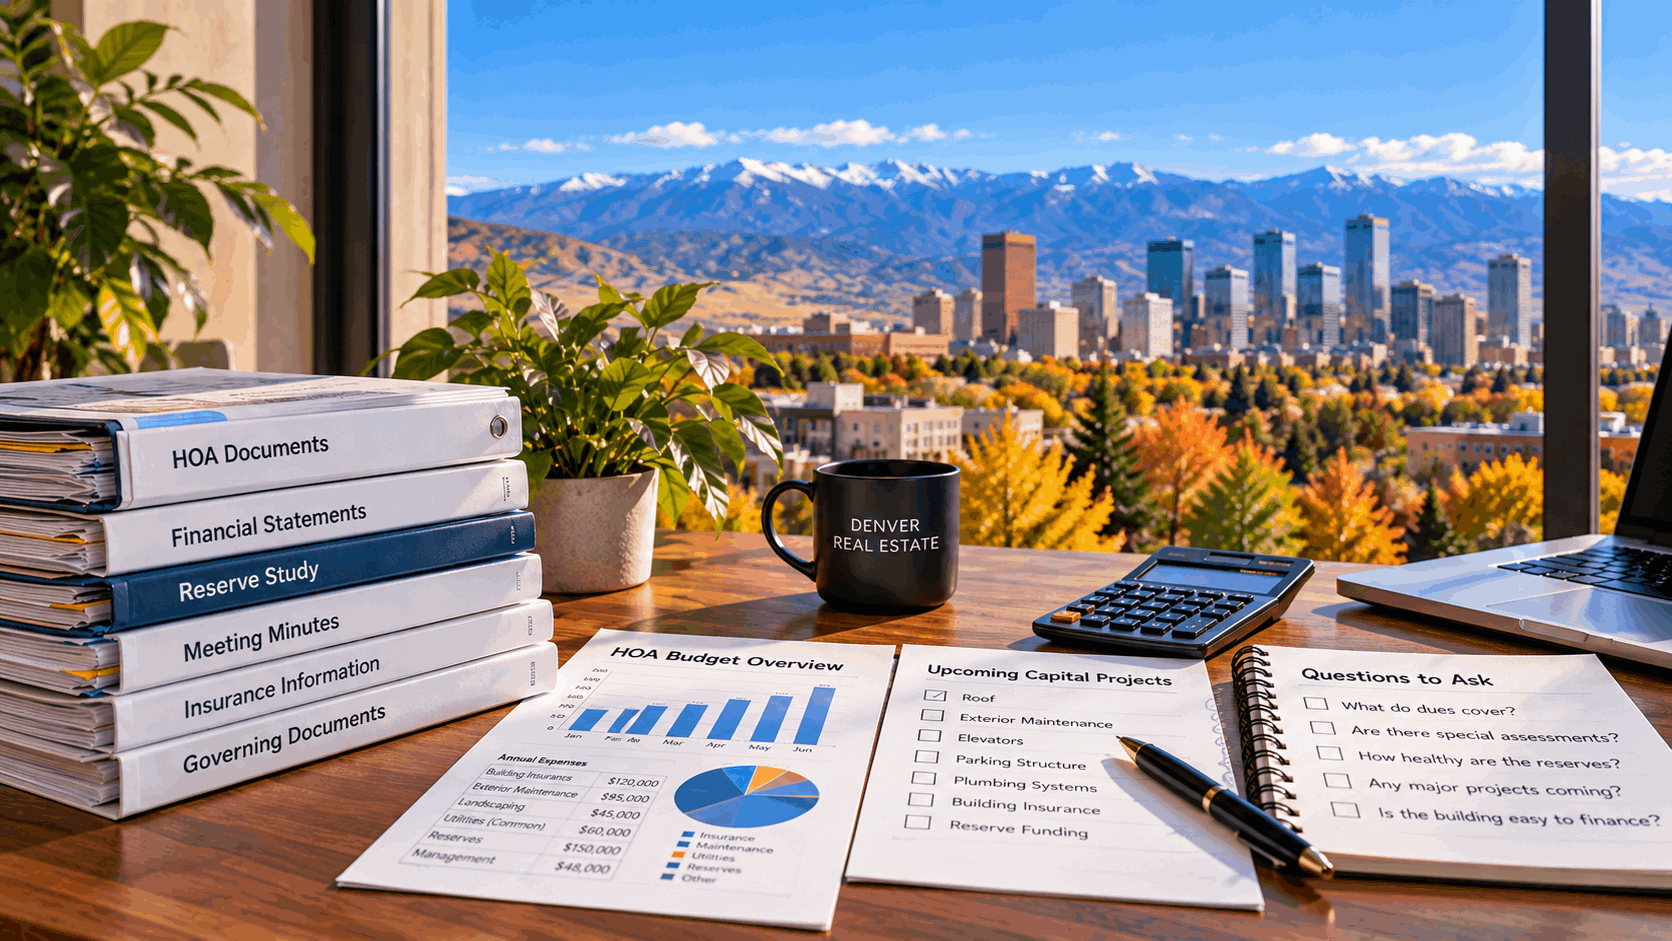
The HOA Budget May Matter Almost as Much as the Condo
This is where buying a condo gets different from buying a typical detached house.
You're not just buying the unit. You're also buying into an association responsible for managing and maintaining the shared property.
Two Denver condos can have similar prices and identical $500 monthly HOA dues while having completely different financial situations.
One association may have healthy reserves, realistic dues, consistent maintenance, and a reasonable plan for future expenses. Another may have kept dues artificially low for years while putting off expensive repairs.
That second condo might look cheaper.
Right up until the owners get hit with a $20,000 special assessment.
That's why I wouldn't automatically choose the condo with the lowest HOA dues. In some cases, unusually low dues can actually make me want to ask more questions, not fewer.
Colorado law has historically required associations to adopt policies addressing reserve studies rather than requiring every existing HOA to complete a reserve study on a universal schedule. New Colorado requirements taking effect in 2026 add reserve-study obligations for certain newly created common-interest communities. The practical takeaway for a buyer is still the same: don't assume the association you're considering has a current reserve study just because it has an HOA.
And don't assume that because an HOA has money in the bank, it has enough money set aside for the work the building will eventually need.
Ask questions. Review the documents. Figure out what you're actually buying into.
What Is a Special Assessment?
A special assessment is an additional charge an HOA can impose on owners when regular dues and available reserves aren't enough to cover a particular expense.
That expense might involve a roof, elevators, exterior work, plumbing, a parking structure, major mechanical systems, insurance-related costs, or another significant repair or improvement.
A special assessment does not automatically make a condo a bad purchase. Buildings need maintenance, and sometimes large expenses are unavoidable.
What I want to understand is why the assessment exists.
Was it an unexpected problem? Was maintenance deferred for years? Were the reserves inadequate? Is this fixing the problem, or is it the first of several expensive projects coming down the road?
And don't stop at assessments that have already been announced.
HOA meeting minutes, budgets, reserve information, insurance documents, maintenance history, and inspection reports can sometimes tell you that a major expense is being discussed long before anyone sends owners a bill.
That's the stuff I want to know before buying, not six months afterward.
Condo Financing Can Depend on More Than Your Credit and Income
This is another area that catches buyers off guard.
You can be completely qualified for a mortgage and still run into a problem financing a particular condominium.
Depending on the loan and project, lenders may need to evaluate aspects of the condominium association itself. Fannie Mae's current project standards include requirements involving project insurance and can require review of issues such as critical repairs, special assessments, inspections, and building condition.
In plain English, your lender may be evaluating both you and the condo project.
That's why I like getting the lender involved early when a buyer is seriously considering a condo. I would much rather identify a financing issue before we've invested a bunch of time and emotional energy into the property than discover it while we're trying to get the deal across the finish line.
A low price isn't much of a bargain if you can't finance the property.
If you're considering buying and want to understand the financing side before you start making offers, you can get pre-approved and start working through the numbers early.
More Inventory Can Create Negotiating Opportunities
Seven-plus months of attached inventory does not mean buyers should start throwing ridiculous lowball offers at every condo in Denver.
That's not a strategy.
What it does mean is that we should look for where the leverage actually exists.
How long has the condo been on the market? Has the price already been reduced? Are there several similar units for sale in the same building? Is the unit vacant? Did a previous contract fall apart? How does its condition compare with the competition? Does the seller have a reason to make a deal?
Then we can look at more than just the price.
Depending on the property and seller, negotiating opportunities might include seller-paid closing costs, repairs, credits toward certain expenses, or concessions that can be used with a lender toward an allowable interest-rate buydown.
With mortgage rates currently above 7%, a properly structured concession can sometimes do more for a buyer's immediate affordability than knocking a few thousand dollars off the purchase price.
That's why I prefer to look at the entire deal rather than obsessing over whether we got another $5,000 off the price.
Let's run the numbers and figure out what actually helps you.
The Cheapest Condo Isn't Necessarily the Best Deal
This might be the most important point in the entire article.
When a market softens, it's easy to start chasing the biggest discount.
A condo that's been listed for months and reduced several times might represent a motivated seller and a great negotiating opportunity.
Or there's a reason nobody wants it.
Maybe the HOA dues are unusually high. Maybe there's a pending assessment. Maybe the association has insurance issues, deferred maintenance, financing problems, or expensive capital projects coming.
Sometimes the market has already figured out that something is wrong.
That doesn't mean I would automatically avoid a property with a long market time. Those can actually be some of the most interesting opportunities. I just want to understand why it's sitting before deciding whether the discount makes sense.
I'll take a slightly more expensive condo in a financially healthy association over a "bargain" in a financial dumpster fire any day.
Denver's Condo Market Is Not One Market
This is especially important in Denver.
A condo in Capitol Hill, a downtown high-rise, a newer unit near Union Station, a townhome in Central Park, and an older attached property in the suburbs can all fall under the broad "attached" category while having completely different buyer pools, HOA structures, insurance situations, amenities, and resale dynamics.
Townhomes can also be very different from traditional condominiums. Some have private entrances, garages, outdoor space, and association responsibilities that look much more like a detached-home community than a downtown condo building.
So I wouldn't look at Denver's 7.21 months of attached inventory and assume every condo buyer automatically has the upper hand.
I would use it as a signal telling us where to start looking.
The market statistics tell us there may be an opportunity. The individual property and association tell us whether it's actually a good one.
What Should You Review Before Buying a Denver Condo?
Before I'd feel comfortable with a condo purchase, I would want to understand more than the condition of the unit and the sales price.
Look at the monthly HOA dues and exactly what they cover. Review the association's budget and available reserve information. Identify current or recently discussed special assessments. Look for major upcoming projects and available information about the building's insurance and physical condition.
HOA meeting minutes can be especially useful because they may show what owners and the board have been talking about before an issue becomes obvious in the financial statements.
Your lender should be involved as well. If there are project-level financing concerns, finding out early is much better than discovering them near closing.
And think ahead to resale.
If something makes a condo difficult to finance or unusually expensive to own today, there's a good chance the person buying it from you someday is going to ask the same questions.
That doesn't automatically make it a bad property. It just needs to be reflected in what you're willing to pay for it.
So, Are Denver Condos a Good Buy Right Now?
For the right buyer and the right property, yes, I think condos and townhomes are one of the more interesting buying opportunities in Denver right now.
Buyers have significantly more inventory than they do in the detached market. The median attached price is lower than it was a year ago. Some sellers have more reason to negotiate. And for buyers who simply can't make the numbers work on a detached house, attached housing can provide another path into homeownership.
But I wouldn't buy a condo simply because prices have softened.
For me, a good condo purchase has to work on three levels:
The unit. The association. Your finances.
If all three make sense, today's market can give you something Denver buyers haven't always had: selection, time to think, and negotiating leverage.
If one of those three doesn't make sense, I don't care how big the price reduction is. It's probably not the deal you think it is.
Frequently Asked Questions
Are Denver condo prices falling?
The September 2026 DMAR report shows a median closed price of $365,500 for attached homes, down 6.28% from September 2025. That's a metro-wide median for completed attached-home sales, not evidence that every individual Denver condo declined by 6.28%.
Is it easier to negotiate on a Denver condo right now?
Potentially, and in some cases, absolutely. Attached homes ended September with 7.21 months of inventory, giving buyers considerably more selection than in the detached segment. Your actual leverage still depends on the individual unit, building, price, condition, days on market, competition, and seller motivation.
Are high HOA dues always a bad sign?
No. Higher dues may reflect substantial services, appropriate maintenance, insurance costs, and responsible reserve funding. Very low dues aren't automatically better if the association isn't saving enough for future expenses. I care much more about what the dues cover and the overall financial health of the HOA than whether the monthly number initially looks high or low.
Can HOA problems affect my mortgage?
Yes. Depending on the property and loan program, condo financing can involve reviewing the condominium project in addition to your personal finances. Insurance, building condition, critical repairs, special assessments, and other project characteristics can affect eligibility. This is something I'd want your lender looking at early.
Is a condo a good option for a first-time Denver buyer?
It can be. The lower median purchase price of attached homes can create a more accessible entry point into the Denver market. Just make sure you're comparing the entire monthly housing expense, including the mortgage, taxes, insurance, HOA dues, and any known assessments, rather than comparing purchase prices alone.
The Bottom Line
I think Denver's condo and townhome market deserves a closer look right now.
Attached homes currently offer substantially more inventory and a lower median price than detached homes, while sellers in some buildings may have more reason to negotiate. For first-time buyers, downsizers, relocation buyers, and anyone who has looked at detached-home prices and thought, "Yeah, that's not happening," there may be another path worth exploring.
But the best opportunity isn't necessarily the condo with the biggest price reduction.
It's the property where the price, HOA finances, building condition, financing, monthly payment, and your longer-term plans all make sense together.
And you don't need to have all of that figured out before talking to me. That's kind of the point.
If a condo or townhome is somewhere on your radar, reach out to me. We can look at what's actually available, run through the numbers, talk about the HOA, and figure out whether this part of the Denver market makes sense for you.
No giant sales pitch. Just a conversation and some actual numbers.
This article is for general informational purposes only and is not legal, lending, insurance, tax, or financial advice. HOA finances, governing documents, assessments, insurance, financing requirements, property conditions, and individual circumstances vary. Buyers should consult the appropriate qualified professionals regarding their specific situation.
Categories
- All Blogs (45)
- Affordability (2)
- Buyers (30)
- Buying Myths (15)
- Buying Tips (18)
- Divorce (1)
- Estate Planning (1)
- First Time Home Buyers (23)
- Home Prices (7)
- Investors (1)
- Market Update (7)
- Mortgage Rates (7)
- Move-Up Buyers (9)
- New Construction (2)
- Probate (1)
- Rent vs. Buy (2)
- Sellers (21)
- Selling Myths (7)
- Selling Tips (14)
Recent Posts

GET MORE INFORMATION